Jayanagar 3rd Block East Bangalore-560011, Karnataka India
Insurance Case Study India: ₹50 Lakh Life Claim Rejected Over Alcohol Disclosure
Insurance Case Study India: ₹50 Lakh Life Claim Rejected Over Alcohol Disclosure
A life insurance claim rejection can create serious financial difficulties for a family, especially when the policy was purchased to provide financial security after the policyholder's death.
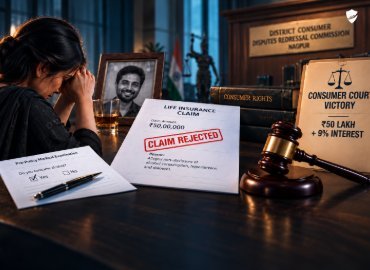
In this case, a man purchased a life insurance policy in April 2021. After his sudden death on 26 January 2023, his widow submitted a death claim for ₹50 lakh.
The insurer rejected the claim, cancelled the policy and later refunded ₹18,713 in premium. The rejection was based on allegations that the deceased had concealed information relating to alcohol consumption, hypertension and diabetes mellitus.
However, an important piece of evidence emerged from the insurer's own pre-policy medical records: the policyholder's alcohol consumption had already been recorded before the policy was issued.
The dispute eventually reached the Nagpur District Consumer Disputes Redressal Commission, which examined whether the life insurance claim rejection was justified.
The Widow Filed a ₹50 Lakh Life Insurance Claim
The deceased purchased the life insurance policy in April 2021. As part of the policy issuance process, he underwent a pre-policy medical examination.
The policy provided life insurance coverage of ₹50 lakh.
On 26 January 2023, the policyholder died suddenly. His widow subsequently approached the insurer and submitted a life insurance death claim seeking payment of the ₹50 lakh sum assured.
Instead of settling the claim, the insurer investigated the circumstances and medical history of the deceased. The claim eventually became a dispute over whether material information had been concealed when the policy was purchased.
This distinction became important because disclosure of material information can play a significant role in underwriting and claim assessment.
The Insurer Rejected the Claim Over Alleged Non-Disclosure
The insurer rejected the ₹50 lakh claim and cancelled the policy. It also sent a cheque for ₹18,713, representing the premium refund.
The insurer alleged that the deceased had concealed a history of chronic alcoholism, hypertension and diabetes mellitus when applying for the policy. According to the insurer, the alleged non-disclosure violated the principle of utmost good faith.
This formed the basis of the life insurance claim repudiation.
The widow challenged the rejection before the Nagpur District Consumer Disputes Redressal Commission.
The central issue was therefore whether the insurer could establish that material information had actually been concealed before the life insurance policy was issued. The pre-policy documentation became particularly important in answering this question.
The Alcohol Habit Had Already Been Disclosed
The Consumer Commission examined the medical records created before the policy was issued.
The pre-policy medical examination form recorded that the insured consumed 90 ml of whisky twice a month and had been doing so for approximately 15 years.
This was significant because the insurer's allegation of concealed alcohol consumption had to be considered against information that had already been recorded during the pre-policy medical process. In other words, the alcohol habit was not information that emerged only after the death claim was submitted.
The Commission also considered the insurer's allegations relating to hypertension and diabetes mellitus. It noted that the pre-policy medical examination conducted by the insurer's panel doctor did not record hypertension or diabetes.
The insurer had therefore issued the policy after conducting its own medical assessment. These records became crucial when the Commission evaluated whether the insurance claim non-disclosure allegation was sufficient to justify rejection.
The case demonstrates why proposal forms, declarations and pre-policy medical records can become extremely important when a life insurance claim dispute involves allegations of concealment.
The Consumer Commission Ordered the ₹50 Lakh Payout
After considering the available evidence, the Nagpur District Consumer Disputes Redressal Commission found the claim rejection unjustified.
The Commission held the insurer guilty of deficiency in service for rejecting the legally payable claim. It directed the insurer to pay the widow the ₹50 lakh life insurance claim.
The claim amount was also ordered to carry 9% annual interest from 30 September 2023.
In addition to the ₹50 lakh claim amount and interest, the Commission awarded:
The outcome demonstrates why the evidence available at the time of policy issuance can become important when an insurer later alleges non-disclosure.
If information was already disclosed through the proposal or medical examination process, those records may become critical when evaluating the validity of a subsequent claim rejection.
What This Life Insurance Claim Case Teaches Policyholders
This insurance claim case study provides several useful lessons for life insurance policyholders and their families.
First, disclose material information accurately when purchasing life insurance. If a proposal form asks about smoking, alcohol consumption, medical conditions, medication or previous treatment, the questions should be answered completely and accurately.
Second, preserve your insurance documents. Policyholders should consider retaining copies of:
These documents can become important if a future life insurance claim rejection is based on alleged concealment or non-disclosure.
Third, a pre-policy medical examination should not be ignored when reviewing a claim dispute. If an insurer conducted medical tests or recorded lifestyle information before issuing the policy, those records may help establish what information was available during underwriting.
Finally, families should carefully examine the reason given for a rejected death claim rather than looking only at the rejection itself. The proposal form, medical records, policy wording and repudiation letter should be reviewed together to understand whether the stated reason for rejection is supported by the available evidence.
Conclusion
This life insurance claim rejection highlights the importance of accurate disclosure as well as the evidence available from the insurer's own pre-policy assessment.
The deceased had purchased the life insurance policy in April 2021. Following his sudden death on 26 January 2023, his widow submitted a claim for ₹50 lakh.
The insurer subsequently rejected the claim, cancelled the policy and sent a cheque refunding ₹18,713 in premium. The insurer alleged that the deceased had concealed a history of chronic alcoholism, hypertension and diabetes mellitus.
However, the pre-policy medical examination form recorded that the insured consumed 90 ml of whisky twice a month and had done so for 15 years. The Commission also noted that the pre-policy medical examination conducted by the insurer's panel doctor did not record hypertension or diabetes.
After considering the evidence, the Nagpur District Consumer Disputes Redressal Commission held the insurer guilty of deficiency in service and directed it to pay the legally payable claim.
The insurer was directed to pay the widow the ₹50 lakh claim amount with 9% annual interest from 30 September 2023. The Commission additionally awarded ₹10,000 for physical and mental harassment and ₹10,000 towards litigation costs.
The broader lesson is clear: policyholders should disclose material information accurately, while claim decisions should be assessed against the actual disclosures and medical evidence available when the policy was issued.
A rejected life insurance claim can create significant financial and emotional difficulties for a family, particularly when the policy was purchased specifically to provide financial protection after the policyholder's death.
If a claim is rejected over alleged non-disclosure, carefully review the proposal form, pre-policy medical examination, declarations, policy wording, medical records and claim rejection letter to understand what information was disclosed and why the insurer rejected the claim.
Contact us today or visit BasketOption.insure, the leading insurance brokers in Bangalore, for your policy, claims review, and expert advisory services. Visit https://basketoption.insure/ or get in touch with our experts today to explore insurance plans that truly care about your needs.
Latest Posts

Our Experts

Frequently Asked Questions
?What was the ₹50 lakh life insurance claim case about?
The case involved a widow whose husband's ₹50 lakh life insurance claim was rejected after his death. The insurer alleged concealment relating to alcohol consumption, hypertension and diabetes.
?When was the life insurance policy purchased?
The deceased purchased the life insurance policy in April 2021.
?When did the policyholder die?
The policyholder died suddenly on 26 January 2023, following which his widow submitted the death claim.
?Why was the ₹50 lakh life insurance claim rejected?
The insurer alleged that the policyholder had concealed a history of chronic alcoholism, hypertension and diabetes mellitus.
?Had the policyholder disclosed his alcohol consumption?
Yes. The pre-policy medical examination form recorded that he consumed 90 ml of whisky twice a month and had done so for approximately 15 years.
?What did the pre-policy medical examination show?
The Consumer Commission noted that the medical examination conducted by the insurer's panel doctor did not record hypertension or diabetes.
?What did the Consumer Commission decide?
The Nagpur District Consumer Disputes Redressal Commission held that rejecting the legally payable claim amounted to deficiency in service and directed the insurer to pay the claim.
?How much was the widow awarded?
The insurer was directed to pay the ₹50 lakh life insurance claim with 9% annual interest from 30 September 2023.
?Was additional compensation awarded?
Yes. The Commission awarded ₹10,000 for physical and mental harassment and ₹10,000 towards litigation costs.
?What is the key lesson from this life insurance claim case?
Policyholders should accurately disclose material information requested during the insurance application and medical examination process and preserve records of those disclosures. Such documents can become important if a future claim is rejected over alleged non-disclosure.