Jayanagar 3rd Block East Bangalore-560011, Karnataka India
Insurance Case Study India: ₹2.20 Crore Insurance Claim Rejected Over Fraud Allegation
Insurance Case Study India: ₹2.20 Crore Insurance Claim Rejected Over Fraud Allegation
An insurer may investigate a claim when it suspects fraud or misrepresentation. But can an already approved insurance claim be withdrawn merely on the basis of suspicion?
A dispute involving a construction company's damaged hydraulic piling rig raised exactly this question.
The machine was severely damaged in a road accident in Odisha. Following surveys and technical assessment, the insurer initially approved an insurance settlement of ₹2,20,84,178. However, the payment was never released.
The insurer subsequently received information suggesting that the supposedly damaged machine was operating commercially in Gujarat. After an investigation, it withdrew the earlier approval and rejected the claim, alleging fraud, misrepresentation and suppression of material facts.
The matter eventually reached the National Consumer Disputes Redressal Commission (NCDRC).
The Commission found that the fraud allegation had not been established with clear and convincing evidence and directed the insurer to pay the ₹2.20 crore claim with interest.
A Road Accident Led to a ₹2.20 Crore Insurance Claim
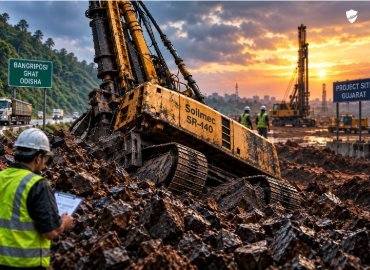
The construction company had purchased a Soilmec SR-40 hydraulic piling rig in September 2009 for approximately ₹3.18 crore, including customs duty.
On March 2, 2013, the machine was being transported from Odisha towards Delhi when it met with an accident at Bangriposi Ghat in Mayurbhanj district, Odisha.
The insurer was informed and a spot survey was conducted the following day.
A technical assessment from the original equipment manufacturer recorded extensive damage to important parts of the piling rig, including its cabin, mast assembly and chassis. The evidence indicated that repairing the machine was technically and economically unviable.
Following the insurance assessment, the final surveyor calculated the net loss at ₹2,20,84,178. The construction company accepted this amount.
The insurer subsequently approved settlement of ₹2,20,84,178 in September 2014 and forwarded the necessary discharge voucher and subrogation documents.
However, despite approving the settlement, the insurer did not release the payment.
Why Did the Insurer Withdraw the Approved Claim?
The dispute changed after the insurer received allegations suggesting that the piling rig had not actually suffered a total loss. An investigator was appointed.
The investigation claimed that a Soilmec SR-40 with a particular serial number was operational at a thermal power project in Gujarat and was being commercially used on lease.
Based on this information, the insurer concluded that the machine damaged in the Odisha accident may have been repaired and returned to commercial operation. The insurer consequently withdrew its earlier approval.
In March 2016, the insurance claim was rejected on allegations of fraud, misrepresentation and suppression of material facts.
This created an unusual situation. The claim had already undergone surveys, the loss had been assessed and a settlement had been formally approved. The insurer was now attempting to reopen that decision based on information obtained later.
The central question therefore became whether the subsequent investigation contained sufficient evidence to establish that the operational machine identified in Gujarat was actually the same piling rig involved in the Odisha accident.
Why the Fraud Allegation Failed Before the NCDRC
The NCDRC examined the evidence relied upon by both sides.
The Commission found that the insurer's investigator did not produce sufficient independent documentary evidence establishing that the machine allegedly operating in Gujarat was the same machine damaged in Odisha. The investigation did not adequately establish the identity, ownership and use of the machine in question.
On the other hand, there was contemporaneous evidence relating directly to the accident. This included the survey reports and the original equipment manufacturer's technical assessment documenting extensive damage to the piling rig. The OEM assessment had indicated that repairs would not be technically and economically viable.
The Commission gave greater weight to this evidence.
An important principle also emerged from the dispute. An insurer can investigate and, where justified, reopen an approved claim if fraud is subsequently discovered. However, an allegation of fraud carries serious consequences and needs to be supported by convincing evidence. Suspicion or a later conflicting opinion alone is not enough to establish fraud.
In this case, the Commission found that the insurer had failed to establish that the construction company obtained approval of the claim through fraud, misrepresentation or suppression of material facts.
NCDRC Ordered Payment of ₹2.20 Crore With Interest
After examining the evidence, the NCDRC held that the rejection of the insurance claim could not be sustained.
The insurer was directed to pay ₹2,20,84,178 to the construction company. The Commission also directed payment of 8% simple interest per annum from September 2, 2013 until final payment.
The insurer was given two months to comply with the order. If payment was delayed beyond that period, the interest applicable to the delayed period would increase to 12% per annum.
The insurer was additionally directed to pay ₹50,000 towards litigation costs.
The outcome demonstrates the importance of evidence when an insurer seeks to reject a claim on allegations as serious as fraud. The existence of suspicious circumstances may justify investigation, but the final claim decision must still be supported by evidence capable of establishing the allegation.
What This Insurance Claim Case Teaches Businesses
This case provides several important lessons for companies holding commercial insurance policies.
First, preserve evidence immediately after a major loss. Survey reports, accident photographs, technical assessments, invoices, equipment records, correspondence and claim documents can become critical if the claim is questioned later.
Second, independent technical evidence can carry significant importance. In this case, the survey reports and OEM assessment created contemporaneous evidence about the condition of the machine following the accident.
Third, businesses should preserve every communication relating to claim approval. Discharge vouchers, settlement communications, emails and other records can establish the history of how the insurer initially assessed the claim.
Finally, allegations of insurance fraud should be treated seriously. Businesses facing such allegations should carefully examine the evidence relied upon by the insurer and compare it against their own technical and documentary records.
A complex commercial insurance claim should ultimately be evaluated on the policy terms, facts and available evidence.
Conclusion
This insurance claim rejection began with a serious road accident involving a hydraulic piling rig and eventually developed into a dispute over total loss, fraud and a ₹2.20 crore insurance settlement.
The insurer initially accepted the survey assessment and approved ₹2,20,84,178. It later withdrew that approval after an investigation suggested that the damaged machine was operating commercially in Gujarat.
But the key issue was evidence. The NCDRC found that the investigation did not sufficiently establish that the machine found in Gujarat was the same piling rig damaged in the Odisha accident.
At the same time, survey reports and the OEM's technical assessment supported the extensive damage suffered by the insured machine.
The Commission therefore held that the insurer had failed to establish fraud, misrepresentation or suppression of material facts and directed payment of the ₹2.20 crore claim with interest.
For businesses, the case highlights a simple but important principle: when a major insurance claim becomes disputed, detailed documentation, technical reports and contemporaneous evidence can become critical.
Has your commercial insurance claim been rejected, delayed, partially settled or questioned after a survey? Start by reviewing your policy wording, survey reports, technical assessments, rejection communication and all supporting documents.
A structured claims review can help businesses understand the insurer's position, identify documentation gaps and determine the appropriate next steps.
Contact us today or visit BasketOption.insure, the leading insurance brokers in Bangalore, for your policy, claims review, and expert advisory services. Visit https://basketoption.insure/ or get in touch with our experts today to explore insurance plans that truly care about your needs.
Latest Posts

Our Experts

Frequently Asked Questions
?What was the ₹2.20 crore insurance claim about?
The claim involved a hydraulic piling rig that suffered extensive damage in a road accident in Odisha while being transported towards Delhi.
?How much did the insurer initially approve?
The insurer approved a settlement of ₹2,20,84,178 based on the assessed loss.
?Why did the insurer later reject the claim?
The insurer received information suggesting that the damaged piling rig was operating commercially in Gujarat. It subsequently alleged fraud, misrepresentation and suppression of material facts.
?Why did the fraud allegation fail?
The NCDRC found that the insurer's investigation did not provide sufficient independent documentary evidence establishing that the machine allegedly operating in Gujarat was the same machine damaged in the accident.
?What evidence supported the construction company's claim?
Survey reports and the original equipment manufacturer's technical assessment documented extensive damage to the piling rig and supported the position that repairs were technically and economically unviable.
?Can an insurer reopen an already approved claim?
The NCDRC recognised that an insurer can reopen an approved claim if fraud is subsequently discovered. However, such action needs to be supported by clear and convincing evidence.
?What did the NCDRC order the insurer to pay?
The insurer was directed to pay ₹2,20,84,178 with 8% simple interest per annum from September 2, 2013 until final payment, subject to the terms of the order.
?Were any litigation costs awarded?
Yes. The insurer was directed to pay ₹50,000 towards litigation costs.
?Why are surveyor and technical reports important in commercial insurance claims?
They can provide contemporaneous evidence regarding the cause, nature and extent of damage and may become important when the claim is assessed or subsequently disputed.
?What is the main lesson from this insurance claim case?
Serious allegations such as fraud require supporting evidence. Businesses should preserve survey reports, technical assessments, correspondence and other documentation relating to a major insurance loss.