Jayanagar 3rd Block East Bangalore-560011, Karnataka India
Insurance Case Study India: Earthquake Insurance Claim Rejected: Hotel's Tax Battle
Insurance Case Study India: Earthquake Insurance Claim Rejected: Hotel's Tax Battle
What happens when a business property is completely destroyed in a natural disaster, its insurance claim is rejected, and the financial consequences continue for years afterward?
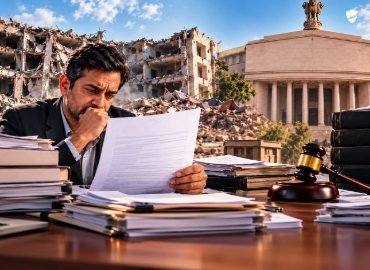
A Gujarat hotel company's experience following the devastating 2001 Gujarat earthquake demonstrates how a major property loss can create both insurance and tax disputes.
The company had spent approximately ₹8.86 crore constructing its hotel building. The earthquake destroyed the property, resulting in a significant financial loss.
An insurance claim was filed, but the insurer rejected it. The rejection resulted in separate litigation over the insurance claim.
Years later, another dispute emerged when the company sold the land on which the destroyed hotel had stood and attempted to account for the destroyed building while calculating its capital loss for income-tax purposes. The Income Tax Department disagreed with the company's treatment.
The matter eventually reached the Income Tax Appellate Tribunal (ITAT), which examined an unusual question: What is the tax treatment of a destroyed insured asset when the insurance company rejects the claim and pays nothing?
The case highlights why property insurance claims can have financial consequences extending far beyond the immediate loss.
A ₹8.86 Crore Hotel Was Destroyed in the Gujarat Earthquake
The company had constructed a hotel property in Gujarat at a cost of approximately ₹8.86 crore.
Then came the devastating Gujarat earthquake of 2001. The hotel building was destroyed.
For a business, destruction of a major property creates more than the immediate physical loss. It can affect operations, asset values, accounting, insurance claims and eventually taxation.
The company had insurance protection and filed a claim following the destruction of the hotel. However, the insurer rejected the claim.
The insurance dispute did not end quickly. Litigation concerning the rejected claim continued before the High Court.
As a result, the company had lost the hotel building but had not received insurance compensation for that loss.
Years later, this unresolved financial history became relevant again when the underlying land was sold.
Why Did the Insurance Rejection Create a Tax Dispute?
When the company eventually sold the land on which the hotel had previously stood, it claimed a substantial capital loss in its income-tax return. The calculation included the value associated with the hotel building that had been destroyed in the earthquake.
The Income Tax Department disagreed with this approach. According to the tax authorities, the land and building were separate capital assets.
Since the building had already been destroyed in the earthquake, its cost could not simply be included while calculating the capital gain or loss arising from the later sale of the land.
This created an unusual problem.
The hotel had unquestionably been destroyed. An insurance claim had been made but rejected. No insurance compensation had been received.
So how should the loss relating to the destroyed building be treated for tax purposes?
The dispute eventually reached the Income Tax Appellate Tribunal.
Why the Rejected Insurance Claim Still Mattered
The ITAT examined the special provisions of income-tax law dealing with destruction or damage to capital assets where insurance compensation is involved.
The Tribunal's reasoning focused on the fact that the destroyed hotel had been an insured asset and an insurance claim had actually been lodged.
The fact that the insurer subsequently rejected the claim did not make the insurance proceedings irrelevant. Instead, the rejection meant that the amount ultimately received from the insurer was effectively nil or zero.
This distinction became important for determining the appropriate tax treatment.
The Tribunal held that the relevant special tax provision dealing with the destruction of insured capital assets could still apply even though the insurance claim had been rejected.
In other words, an insurance claim did not have to result in a successful payout for the insurance-related tax provision to become relevant. The rejected claim could effectively represent zero insurance compensation.
ITAT Allowed the Capital Loss Claim Under Tax Law
The timing of the loss also became important. The company had attempted to account for the destroyed building when it later sold the underlying land.
However, the ITAT distinguished between the land and the hotel building. The destruction of the building was one event. The later sale of the land was another.
The capital loss associated with the destroyed insured building therefore had to be considered according to the special provision applicable to destruction of insured capital assets and in the appropriate assessment year.
The Tribunal held that the rejected insurance claim could be treated as resulting in zero compensation for the relevant tax computation.
Accordingly, the company was entitled to claim the capital loss relating to the destroyed hotel building under the applicable tax-law framework in the relevant assessment year.
The case therefore demonstrates how an unsuccessful insurance claim can continue to have significant accounting and tax consequences long after the physical loss occurred.
What This Earthquake Insurance Case Teaches Businesses
The first lesson is that the financial impact of a major property loss does not necessarily end when an insurer rejects the claim. A rejected insurance claim can lead to litigation and may also affect accounting and taxation.
Second, businesses should maintain detailed records following a major loss. Construction costs, asset valuations, insurance policies, claim forms, survey reports, repudiation letters, correspondence, accounting records and legal documents can become important years after the original event.
Third, land and buildings may receive different legal and tax treatment even when they form part of the same commercial property. The destruction of a building and the subsequent sale of the underlying land should therefore not automatically be treated as one financial event.
Fourth, businesses should review property insurance before a disaster occurs. Policy limits, exclusions, deductibles, valuation methods and other conditions can significantly affect how much protection is actually available following a catastrophic event.
Finally, major commercial losses can involve multiple areas of expertise. Insurance, legal, accounting and taxation issues may all arise from the same event.
For businesses holding valuable property, proper risk assessment and documentation can therefore be as important as purchasing the policy itself.
Conclusion
The destruction of the hotel during the 2001 Gujarat earthquake created financial consequences that continued for years.
The company had invested approximately ₹8.86 crore in constructing the hotel building. After the earthquake destroyed the property, an insurance claim was filed but rejected, resulting in a prolonged insurance dispute.
Years later, when the company sold the underlying land, another dispute emerged over whether the value of the destroyed building could be considered while calculating the company's capital loss.
The ITAT held that the special tax provision relating to destroyed insured assets remained relevant even though the insurer had rejected the claim. The rejected claim effectively meant that the company had received zero insurance compensation.
The company could therefore claim the relevant capital loss under the applicable tax provisions in the appropriate assessment year.
The broader lesson for businesses is clear:
A major property loss can create consequences far beyond the insurance claim itself. Proper insurance coverage, documentation and financial records can remain important for years after the original loss.
Property insurance should be reviewed based on the actual value and risks associated with your business assets—not simply on whether a policy exists.
Businesses should periodically review property values, sum insured, policy conditions, exclusions and potential coverage gaps before a major loss occurs.
Contact us today or visit BasketOption.insure, the leading insurance brokers in Bangalore, for your policy, claims review, and expert advisory services. Visit https://basketoption.insure/ or get in touch with our experts today to explore insurance plans that truly care about your needs.
Latest Posts

Our Experts

Frequently Asked Questions
?What happened to the hotel in this case?
The hotel building in Gujarat was destroyed during the 2001 Gujarat earthquake.
?How much had the company spent constructing the hotel?
The company had spent approximately ₹8.86 crore constructing the hotel property.
?Did the company have insurance for the hotel?
Yes. An insurance claim was filed following the destruction of the hotel.
?Was the earthquake insurance claim paid?
No. The insurer rejected the claim, which led to a separate legal dispute.
?Why did the case later become an income-tax dispute?
When the company later sold the land, it attempted to account for the destroyed building while claiming a capital loss. The Income Tax Department challenged this treatment.
?Why were the land and hotel building treated separately?
The tax authorities considered the land and building to be separate capital assets. The building had already been destroyed before the land was subsequently sold.
?What did the ITAT say about the rejected insurance claim?
The Tribunal held that the relevant special tax provisions concerning destruction of insured assets could still apply even though the insurance claim had been rejected.
?What does zero insurance compensation mean in this case?
Because the insurer rejected the claim and no compensation was received, the insurance amount could effectively be treated as nil or zero for the relevant tax computation.
?Was the company allowed to claim a capital loss?
Yes. The Tribunal held that the capital loss relating to the destroyed insured asset could be claimed under the applicable tax provisions in the relevant assessment year.
?What should businesses learn from this case?
Businesses should maintain detailed property, insurance, claim and financial records after major losses because the consequences can extend into insurance litigation, accounting and taxation for years.