Jayanagar 3rd Block East Bangalore-560011, Karnataka India
Insurance Case Study India: ₹18 Lakh Insurance Claim Rejected Over Rare Disease
Insurance Case Study India: ₹18 Lakh Insurance Claim Rejected Over Rare Disease
Can an insurance company reject a claim based on policy conditions that it cannot prove were communicated to the policyholder?
A case involving an ₹18 lakh home loan insurance claim highlights the importance of transparency in insurance contracts.
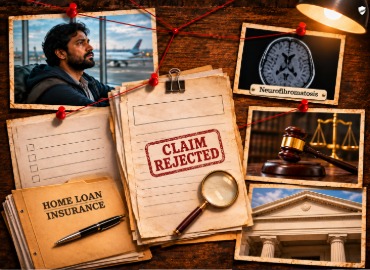
Manoj Kumar purchased five-year insurance coverage linked to his housing loan by paying a one-time premium of approximately ₹1.37 lakh. While working in Oman, he developed a rare medical disorder that forced him to leave his overseas employment and return to India.
When he submitted an insurance claim, the insurer rejected it, citing restrictions under the policy.
However, the insurer could not satisfactorily establish that these restrictive conditions had been supplied or explained to the policyholder.
The dispute eventually reached the Chandigarh State Consumer Commission, which upheld an order directing the insurer to pay ₹18 lakh with interest and compensation.
An ₹18 Lakh Home Loan Insurance Policy and a Rare Diagnosis
Manoj Kumar had taken a housing loan of approximately ₹18 lakh.
To obtain insurance protection linked to the loan, he paid a one-time premium of around ₹1.37 lakh for five years of coverage.
At the time, he was working in Oman.
In 2019, Manoj Kumar developed serious health complications and was diagnosed with Neurofibromatosis, a rare disorder associated with tumours developing along nerves.
His condition progressively worsened, making it impossible for him to continue working abroad.
He returned to India for medical treatment.
Facing financial difficulties following his illness and loss of overseas employment, he sought the ₹18 lakh insurance benefit associated with his housing loan.
However, the insurer refused to settle the claim.
Why Did the Insurer Reject the ₹18 Lakh Claim?
The insurer argued that the policy covered only seven specified major illnesses and medical procedures.
According to the insurer, Neurofibromatosis was not included among those covered conditions.
On that basis, the company rejected Manoj Kumar's claim.
However, the dispute raised another important question.
Had the insurer actually supplied and explained those restrictive policy conditions to the customer?
During the consumer proceedings, the insurer could not satisfactorily prove that the relevant terms had been delivered, communicated or acknowledged by Manoj Kumar.
This became a central weakness in the insurer's position.
The case demonstrates why insurance exclusions should not merely exist in policy documents. Their communication to the policyholder can become a significant issue when a claim is disputed.
Why the Policy Paperwork Became the Deciding Factor
Insurance contracts contain terms defining the benefits available, the circumstances covered and the applicable restrictions.
However, customers need access to those terms to understand what they are purchasing.
In this case, the insurer relied on a restricted list of covered illnesses and procedures.
But it could not satisfactorily establish that the policyholder had received or acknowledged those conditions.
The consumer forum considered this failure significant.
The dispute illustrates why policy documentation matters beyond the premium receipt.
A complete insurance file should ideally include the proposal form, policy schedule, benefit details, exclusions, terms and conditions, and records showing how the documents were delivered.
These records can help establish what information was available to the customer when the policy was purchased.
For policyholders, retaining the actual documents received can become valuable evidence if an insurer later relies on a disputed exclusion.
Consumer Commission Orders ₹18 Lakh With Interest
After the claim was rejected, Manoj Kumar approached the District Consumer Commission.
The Commission considered the insurer's reliance on restrictive policy conditions and its inability to satisfactorily prove that those conditions had been communicated.
It ruled in favour of the policyholder.
The Commission directed the insurer to pay:
The insurer appealed before the Chandigarh State Consumer Commission.
However, the State Commission declined to interfere with the District Commission's findings and upheld the order.
The case demonstrates that policy-document delivery and communication can become decisive issues in insurance claim disputes.
What This Insurance Claim Rejection Case Teaches Policyholders
The first lesson is to request complete policy wording before purchasing insurance.
A premium receipt or brief benefit summary may not explain every limitation.
Second, customers should understand exactly which illnesses, events and benefits are covered, particularly when purchasing insurance linked to a home loan.
Third, verbal assurances should not replace written documentation.
Policyholders should preserve their proposal forms, benefit schedules, exclusions and communication records.
Fourth, when an insurance claim is rejected, customers should request the exact policy clause relied upon by the insurer.
They should then compare that clause with the documents actually received when the policy was issued.
Finally, insurers and intermediaries should maintain clear records demonstrating that important terms were supplied and communicated.
Policy clarity should begin when insurance is sold, not when a claim is rejected.
Conclusion
The ₹18 lakh insurance claim rejection involving Manoj Kumar highlights the importance of clear policy documentation.
After developing Neurofibromatosis while working in Oman, Manoj Kumar could no longer continue his overseas employment and sought the insurance benefit linked to his housing loan.
The insurer rejected the claim, arguing that the disorder was not among the seven specified covered conditions.
However, the insurer could not satisfactorily prove that the restrictive terms had been communicated to the policyholder.
The District Consumer Commission ordered payment of ₹18 lakh with interest and compensation, and the Chandigarh State Consumer Commission upheld that decision.
The key lesson is simple: Policyholders should know what their insurance covers, and insurers should be able to establish which terms were communicated when the policy was issued.
Before purchasing insurance linked to a home loan, review the covered benefits, exclusions and conditions that may affect future claims.
If your claim has been rejected, reviewing the policy documents and repudiation reasons can help identify the appropriate next steps.
Contact us today or visit BasketOption.insure, the leading insurance brokers in Bangalore, for your policy, claims review, and expert advisory services. Visit https://basketoption.insure/ or get in touch with our experts today to explore insurance plans that truly care about your needs.
Latest Posts
Our Experts

Frequently Asked Questions
?What was the ₹18 lakh insurance claim case about?
The case involved Manoj Kumar, who sought an ₹18 lakh insurance benefit linked to his housing loan after developing Neurofibromatosis and becoming unable to continue working abroad.
?How much insurance premium did Manoj Kumar pay?
He paid a one-time premium of approximately ₹1.37 lakh for five years of coverage.
?What medical condition did the policyholder develop?
He was diagnosed with Neurofibromatosis in 2019 while working in Oman.
?Why did the insurer reject the claim?
The insurer argued that Neurofibromatosis was not among the seven specified illnesses and medical procedures covered under the policy.
?What was the main problem with the insurer's defence?
The insurer could not satisfactorily establish that the restrictive policy conditions had been supplied, explained or acknowledged by the policyholder.
?What did the District Consumer Commission order?
The Commission directed payment of ₹18 lakh with 6% annual interest from 4 June 2019 until payment, plus ₹20,000 towards harassment and litigation expenses.
?Did the insurer appeal the decision?
Yes. The insurer challenged the District Commission's order before the Chandigarh State Consumer Commission.
?What did the Chandigarh State Consumer Commission decide?
It refused to interfere with the District Commission's order and upheld the decision.
?Can an insurance company reject a claim based on exclusions?
An insurer may rely on applicable policy exclusions. However, disputes can arise over whether those conditions formed part of the contract, were properly communicated and apply to the particular claim.
?What should policyholders do after an insurance claim rejection?
They should obtain the repudiation letter, review the specific exclusion relied upon and compare it with the policy documents actually supplied to them.