Jayanagar 3rd Block East Bangalore-560011, Karnataka India
Insurance Case Study India: ₹6.75 Lakh Motor Claim Rejected Over No Claim Bonus
Insurance Case Study India: ₹6.75 Lakh Motor Claim Rejected Over No Claim Bonus
Can an insurance company reject an entire motor insurance claim because the policyholder received an incorrect No Claim Bonus (NCB)?
A Delhi consumer case involving a ₹6.75 lakh motor insurance claim highlights an important responsibility shared by insurers and policyholders.
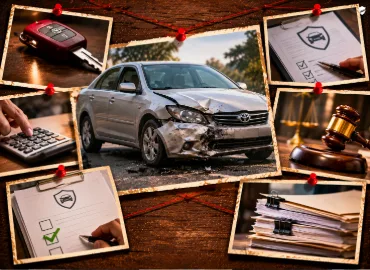
Shadi Lal Kapoor insured his Toyota Corolla with L&T General Insurance. Following an accident, he submitted a claim for substantial vehicle damage.
However, the insurer rejected the claim because Kapoor had received a 25% No Claim Bonus despite having made claims under his previous insurance policy.
The dispute eventually reached the Delhi State Consumer Disputes Redressal Commission.
The Commission found that the insurer had failed to verify NCB eligibility within the prescribed period under the Indian Motor Tariff.
It also held that the policyholder should not receive the full benefit of an incorrect declaration.
The result was a reduced award of ₹5,06,250 instead of ₹6,75,000.
A ₹6.75 Lakh Motor Insurance Claim After a Car Accident
Shadi Lal Kapoor purchased motor insurance for his Toyota Corolla from L&T General Insurance Company Ltd.
The policy covered the period from 7 September 2011 to 6 September 2012.
The important policy details were:
During the policy period, the vehicle met with an accident and suffered substantial damage.
Kapoor reported the incident to the insurer, which arranged an inspection.
However, on 21 January 2013, the insurance company repudiated the claim.
The reason was not the accident itself but the No Claim Bonus declaration made when the policy was purchased.
Why Did the Insurer Reject the Claim Over a 25% NCB?
A No Claim Bonus is a discount on the own-damage portion of motor insurance premiums, generally earned for claim-free policy periods.
Kapoor had received a 25% NCB while purchasing his policy.
However, the insurer subsequently obtained information showing that he had made two claims under his previous policy with ICICI Lombard.
This meant he was not eligible for the discount.
L&T General Insurance argued that the incorrect declaration amounted to a breach of policy conditions.
It relied on General Regulation 28 of the Indian Motor Tariff and the policy declaration to justify rejecting the claim entirely.
Kapoor disputed the decision.
He maintained that he had informed the insurance agent about his previous claims and that the insurer should have verified his eligibility with the previous insurance company.
The dispute therefore raised an important question: could the insurer reject the entire accident claim despite failing to complete its own verification obligations?
How the Insurer Failed Its 21-Day Verification Duty
The Commission examined General Regulation 27 (GR 27) of the Indian Motor Tariff.
Under the tariff framework applicable to the case, an insurer granting NCB was required to seek confirmation from the previous insurer within 21 days of granting coverage.
The previous insurer was required to respond within 30 days of receiving the enquiry.
The Commission found that L&T General Insurance had not fulfilled its verification obligation.
Had the insurer checked the previous policy within the prescribed period, the incorrect NCB declaration could have been identified earlier.
The Commission also considered the legal principles relating to misrepresentation under Sections 18 and 19 of the Indian Contract Act, 1872.
The insurer had an opportunity to verify the information through ordinary diligence but failed to do so.
Consequently, the Commission held that complete repudiation of the motor insurance claim was unjustified.
However, this did not mean Kapoor was entitled to the entire original award.
Why the Commission Reduced the Award to ₹5.06 Lakh
The District Consumer Forum had initially ruled in Kapoor's favour.
It directed payment of ₹6,75,000 with 9% interest from the date of claim until realisation, along with ₹20,000 and ₹50,000 under the additional compensation and cost directions.
L&T General Insurance appealed.
On 6 October 2020, the Delhi State Consumer Commission partly allowed the appeal.
It held that although the insurer had failed to verify the NCB declaration, Kapoor had also received a discount to which he was not entitled.
The Commission therefore reduced the original award by 25%.
The revised amount was:
₹6,75,000 × 75% = ₹5,06,250
The original directions concerning interest, compensation and costs remained unchanged.
The decision balanced the insurer's failure to verify the declaration against the policyholder's incorrect claim of NCB eligibility.
What This Motor Insurance Claim Rejection Teaches Car Owners
The first lesson is to disclose previous motor insurance claims accurately.
An incorrect NCB declaration can create serious complications during claim settlement.
Second, policyholders should verify their NCB percentage before renewing or switching insurers.
Third, insurers also have responsibilities under the applicable policy and regulatory framework.
In this case, the insurer's failure to complete the required verification prevented it from justifying complete repudiation.
Fourth, an incorrect NCB declaration does not necessarily result in complete claim rejection in every dispute.
The outcome depends on the applicable rules, policy conditions and specific circumstances.
Finally, retain previous policy schedules, claim records and renewal documents.
These records can help establish NCB eligibility and prevent avoidable disputes.
Conclusion
The ₹6.75 lakh motor insurance claim rejection involving Shadi Lal Kapoor demonstrates how an incorrect No Claim Bonus declaration can affect insurance settlement.
The insurer rejected the accident claim because Kapoor had received a 25% NCB despite making previous insurance claims.
However, the Delhi State Consumer Commission found that the insurer had failed to verify his eligibility within the prescribed period under GR 27.
The Commission ruled that complete repudiation was unjustified but also held that the policyholder should not benefit fully from an incorrect declaration.
The award was therefore reduced to ₹5,06,250, while the original interest, compensation and cost directions remained unchanged.
The lesson is clear: policyholders must disclose previous claims accurately, and insurers must fulfil their applicable verification responsibilities.
Contact us today or visit BasketOption.insure, the leading insurance brokers in Bangalore, for your policy, claims review, and expert advisory services. Visit https://basketoption.insure/ or get in touch with our experts today to explore insurance plans that truly care about your needs.
Latest Posts
Our Experts

Frequently Asked Questions
?What was the ₹6.75 lakh motor insurance case about?
The case involved Shadi Lal Kapoor, whose motor insurance claim was rejected because he had received an incorrect 25% No Claim Bonus.
?Which insurance company rejected the claim?
L&T General Insurance Company Ltd. rejected the claim.
?What was the insured value of the Toyota Corolla?
The vehicle's Insured Declared Value was ₹6,75,000.
?Why was Kapoor ineligible for the No Claim Bonus?
He had made two claims under his previous motor insurance policy with ICICI Lombard.
?What is a No Claim Bonus in motor insurance?
A No Claim Bonus is a discount on the own-damage premium generally earned when no claim is made during the relevant policy period.
?What did GR 27 require in this case?
Under the applicable Indian Motor Tariff framework, the insurer granting NCB was required to seek confirmation from the previous insurer within 21 days of granting coverage.
?Why did the Commission reject complete claim repudiation?
The Commission found that the insurer had failed to fulfil its NCB verification obligation.
?Why was the claim amount reduced by 25%?
The policyholder had received a 25% discount to which he was not entitled. The Commission therefore reduced the original award proportionately.
?What was the final amount awarded?
The principal award was reduced to ₹5,06,250. The original interest, compensation and cost directions remained unchanged.
?What should car owners check before renewing motor insurance?
They should verify previous claim history, NCB eligibility, policy details, Insured Declared Value and applicable coverage conditions.