Jayanagar 3rd Block East Bangalore-560011, Karnataka India
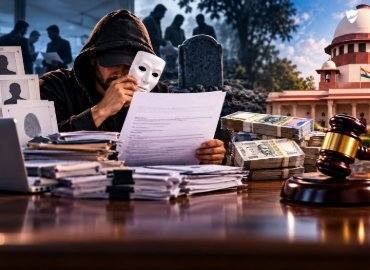
Insurance Case Study India: ₹1.19 Crore Fake Death Claim Insurance Scam
Insurance Case Study India: ₹1.19 Crore Fake Death Claim Insurance Scam
Can life insurance policies be created using false information and later turned into fraudulent death claims?
A case involving an alleged ₹1.19 crore insurance fraud shows how fake identities, fabricated documents and false death claims can allegedly be used as part of an organised insurance scam.
According to the investigation referred to in the court proceedings, a group of people allegedly created fraudulent life insurance policies and later submitted false death claims to obtain insurance payouts.
The alleged scheme involved fake identities and documents, with people shown as deceased for the purpose of making insurance claims. Investigators also alleged that part of the insurance proceeds eventually reached the bank account of one of the accused.
The accused sought anticipatory bail, arguing that he was innocent and that money credited to his account was merely repayment of a personal loan.
However, the court considered the allegations and investigation serious enough to refuse anticipatory bail.
The case demonstrates how life insurance fraud involving fake death claims can involve not only fabricated documents but also financial transactions, impersonation and multiple people allegedly working together.
How the ₹1.19 Crore Fake Death Claim Scam Allegedly Worked
According to the allegations before the court, the fraud involved creating insurance policies using false information and subsequently submitting fraudulent death claims.
The alleged scheme was not limited to one questionable document or transaction. Investigators claimed that fake identities and documents were used as part of the process.
Certain individuals were allegedly represented as dead so that death benefits could be claimed from insurance companies. The total amount associated with the alleged fraudulent insurance claims was approximately ₹1.19 crore.
Such allegations are particularly serious in life insurance because death claims can involve substantial payouts.
Insurance companies therefore examine documents such as death certificates, identity records, nominee information, policy details, medical records and banking information while processing claims.
In this case, the investigation went beyond the documents submitted with the claims. Authorities also examined the movement of money after the alleged insurance payouts.
Bank Transactions Became Important to the Investigation
Financial transactions became an important part of the case against the accused.
Investigators alleged that a portion of the money connected with the fraudulent insurance claims had been transferred to the accused through his bank account.
The accused disputed the allegation. He argued that the money credited to his account was not his share of fraudulent insurance proceeds. According to his defence, the amount represented repayment of a personal loan.
However, the investigation also alleged a broader role. The material considered during the bail proceedings allegedly connected the accused with the handling of fake insurance claims.
It was also alleged that he communicated with people while representing himself as being associated with an insurance company's claims department.
These circumstances contributed to the court's assessment of the seriousness of the allegations.
The case demonstrates why financial trails can become significant in an insurance fraud investigation. Bank transfers can help investigators examine where claim proceeds went, who ultimately received the money and whether transactions correspond with explanations provided by the people involved.
Why the Court Rejected Anticipatory Bail
The accused approached the court seeking anticipatory bail. His position was that he was innocent and had been falsely implicated.
He also sought to explain the money received in his bank account as repayment of a personal loan rather than proceeds connected with insurance fraud.
The court, however, considered the nature of the allegations and the investigation. The alleged fraud involved fake insurance claims, fabricated information and substantial amounts of money.
The material placed before the court also indicated an alleged role for the accused in the insurance-claim process.
Given the seriousness and organised nature of the alleged fraud, the court did not consider it appropriate to grant anticipatory bail. The application was therefore rejected.
Importantly, rejection of anticipatory bail should not be confused with a final conviction.
A bail proceeding determines whether an accused should receive protection from arrest under the applicable circumstances. The ultimate question of criminal guilt is determined through the criminal justice process based on the evidence.
Why Fake Death Claims Are a Serious Insurance Fraud Risk
A life insurance policy is intended to provide financial protection to beneficiaries following the death of an insured person, subject to the policy terms. A fake death claim attempts to misuse that protection.
Such fraud can involve fabricated death certificates, false identities, manipulated policy information, impersonation, fraudulent bank accounts or coordinated activity among multiple people.
This is why life insurance claims can involve extensive verification. Insurers may examine the identity of the insured and nominee, cause and circumstances of death, medical history, policy information and supporting documentation.
Suspicious financial transactions can also become relevant where fraud is suspected.
Organised insurance fraud creates consequences beyond the immediate financial loss. It can lead insurers to increase scrutiny of unusual claims and strengthen verification procedures.
This makes accurate documentation particularly important for genuine policyholders and nominees.
Genuine claimants should maintain policy records, identity documents, nominee information, medical records and other documents that may be required during claim processing.
What This ₹1.19 Crore Insurance Fraud Case Teaches
The case demonstrates that insurance fraud can extend far beyond submitting one false document. Investigators may examine identities, claim documents, communications, bank accounts and the movement of insurance proceeds.
Second, digital and financial trails can become important evidence. Even where a person provides an alternative explanation for a bank transfer, investigators and courts can examine that explanation alongside the broader evidence.
Third, impersonating insurance representatives or claims personnel can significantly increase the seriousness of suspected fraudulent activity.
Fourth, organised insurance fraud can ultimately affect genuine customers. When insurers encounter sophisticated fraudulent claims, verification and investigation processes may become more rigorous.
Finally, policyholders and nominees should ensure that information submitted during both policy issuance and claim settlement is accurate and supported by genuine documentation.
Insurance is built on disclosure and verifiable information. Attempting to manipulate that process through fabricated identities, documents or death claims can lead to serious criminal investigation and legal consequences.
Conclusion
The alleged ₹1.19 crore fake death claim insurance scam demonstrates how sophisticated insurance fraud can involve multiple layers.
According to the investigation discussed in the court proceedings, fraudulent life insurance policies and false death claims were allegedly created using fake identities and documents.
Investigators also alleged that part of the claim proceeds reached the accused's bank account and that he had participated in communications connected with insurance claims.
The accused denied involvement and argued that money received by him was repayment of a personal loan.
However, considering the seriousness and organised nature of the allegations and the investigation material before it, the court rejected his request for anticipatory bail.
The case reinforces an important point:
Insurance fraud investigations do not stop at the claim form. Documents, identities, communications and financial transactions can all become part of the investigation.
At the same time, rejection of anticipatory bail is not itself a final finding that the accused is guilty. Criminal liability must ultimately be determined according to the evidence and applicable legal process.
Insurance claims should always be supported by accurate information, genuine documents and complete disclosure.
For genuine policyholders, keeping policy documents, nominee information, medical records and other important records organised can help make the claims process easier to navigate.
Contact us today or visit BasketOption.insure, the leading insurance brokers in Bangalore, for your policy, claims review, and expert advisory services. Visit https://basketoption.insure/ or get in touch with our experts today to explore insurance plans that truly care about your needs.
Latest Posts

Our Experts

Frequently Asked Questions
?What was the ₹1.19 crore insurance fraud case about?
The case involved allegations that fraudulent life insurance policies and fake death claims were used to obtain insurance payouts illegally.
?How much money was allegedly involved?
The alleged fraudulent insurance claims were stated to involve approximately ₹1.19 crore.
?What methods were allegedly used in the insurance scam?
According to the investigation referred to during the court proceedings, the alleged scheme involved fake identities, false documents and fraudulent death claims.
?Why were bank transactions important?
Investigators alleged that part of the money associated with the insurance claims was transferred to the accused through his bank account.
?How did the accused explain the money?
The accused argued that the money received by him represented repayment of a personal loan rather than proceeds of insurance fraud.
?Was impersonation also alleged?
According to the case material, the accused was allegedly involved in communications while representing himself as connected with an insurance company's claims department.
?What did the court decide?
The court rejected the accused's application for anticipatory bail after considering the nature and seriousness of the alleged fraud and the investigation material.
?Does rejection of anticipatory bail mean the accused was convicted?
No. Rejection of anticipatory bail is not the same as a final finding of guilt or a criminal conviction.
?How can insurers identify fake death claims?
Insurers may verify identity records, death documentation, nominee information, medical records, policy details and other supporting evidence. Suspicious cases may receive additional investigation.
?What can genuine policyholders learn from this case?
Policyholders and nominees should provide accurate information, maintain genuine documentation and keep important policy and claim records organised to support legitimate claims.